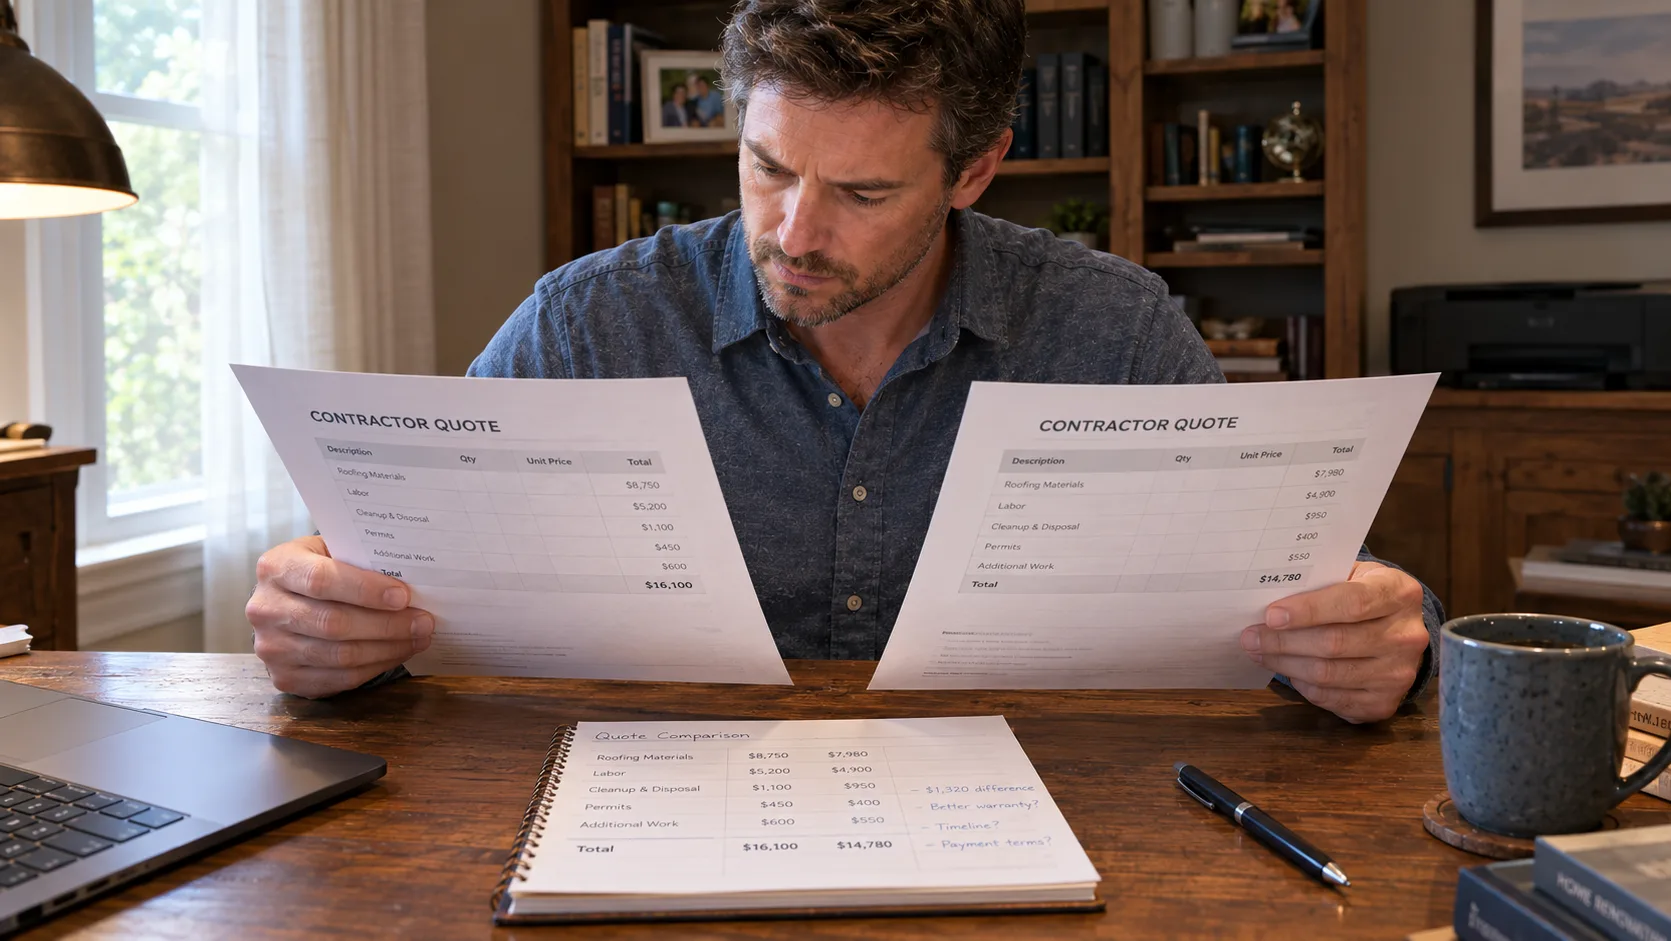
When two contractors — or a contractor and a bank — each hand you a financing offer for the same roof, the two offers are built to look different on purpose. One leads with the monthly payment, the other leads with the rate, and by the time you've stared at both, you're comparing apples to lawnmowers. After a decade of helping homeowners sort through these pitches, I've learned that the difference between a good decision and a costly one usually comes down to roof financing contract terms — and those terms don't compare themselves. They only compare when you force both offers onto the same page. Here's the method I've used for years, and it takes about twenty minutes with a pen.
Why Two Offers Never Look the Same at First Glance
Financing offers are marketing documents as much as they are financial ones. The contractor's partner lender wants you to see a small number that fits your monthly budget, so it prints the payment in large type. The credit union wants you to see a low rate, so it prints the APR in large type. Neither is lying — both numbers are real — but each number is only one piece of a much larger machine. If you compare the pieces that each offer chooses to highlight, you'll never see the full picture of either one. The fix is simple and a little boring: list the same fields for both offers, fill them in from the actual paperwork, and read down the columns instead of across the headlines.
The Six Fields That Matter
Forget the marketing. Every financing offer, no matter who writes it, can be reduced to the same six fields, and those six fields are the only ones I let myself compare:
Amount financed — the price of the roof plus anything folded into the loan
APR — the true annual rate, including certain fees, not the teaser rate
Term — how many months you're actually scheduled to pay
Monthly payment — the amount due each month, for every month of the term
Fees added to the principal — origination, documentation, or processing charges that increase what you owe from day one
Total of payments — the sum of every payment over the full life of the loan
That last field is the one almost nobody looks at, and it's the one that tells you which offer is actually cheaper. A monthly payment is a cash-flow number. The total of payments is a cost number. You need both, but you decide with the cost number. And this list works precisely because it forces both sales pitches into the same six rows — the only honest way to compare roof financing contract terms.
Two Offers for the Same Roof: A Worked Example
Let me show you the method on a real-shaped example, with illustration numbers so you can follow the arithmetic. These are not quotes from any lender — rates vary by lender, credit, and market — but the structure is exactly what I see on kitchen tables across Texas. Say the same roof costs $18,000, and two offers arrive for it.
Field | Offer A — contractor's partner lender | Offer B — local credit union |
|---|---|---|
Amount financed | 750 paperwork fee) | $18,000 |
APR | about 7% (illustrative) | about 7% (illustrative) |
Term | 120 months | 60 months |
Monthly payment | about $225 | roughly $356 |
Fees added to principal | $750 | none |
Total of payments | about $27,000 | about $21,400 |
Here's how the sales conversation actually goes with these two. Offer A's rep leads with the number that jumps off the page: about 356. That's a real difference — roughly $130 a month of breathing room. Offer B's lender, by contrast, hands you a plain rate sheet and lets the numbers sit there. On the surface, the contractor's offer looks friendlier, and a lot of homeowners would sign it right there in the office.
But read down the columns before you read across them. Offer A quietly added 225 a month for a full decade. The total of payments on Offer A comes to roughly 18,000 roof. Offer B, at about 21,400. Offer A isn't cheaper — it's about $5,600 more expensive, and it keeps you in debt for five extra years. The "better" pitch loses the moment the roof financing contract terms are compared line by line.
That 356 payment, Offer A may still be the workable choice — that's a legitimate decision. But it should be a decision you make with your eyes open, knowing you're paying roughly $5,600 for the privilege of a smaller monthly number. The method doesn't tell you which offer to pick. It tells you what you're actually picking between.
The Comparison Steps, In Order
Here's the routine I walk through with every homeowner, and you can steal it. It works whether you're comparing two lenders, two contractors, or a contractor and your own bank:
Write the roof price at the top of a blank page, and confirm both offers are financing that same price and the same scope of work.
Draw two columns and list the same six fields for each offer — amount financed, APR, term, monthly payment, fees, and total of payments.
Fill every field from the written disclosure documents, not from what anyone said out loud.
Subtract: compare the totals of payments first, then look at the monthly difference and the term difference.
Check the fine print both offers share — prepayment penalties, whether the rate is fixed, and what happens if a payment is late.
Take the page home and sleep on it before you sign either one.
If an offer can't fill in a field, that's the most important finding of your whole comparison. A financing offer that won't state its total of payments in writing is telling you something, and it isn't good.
Let a Loan Calculator Double-Check the Math
One more habit worth building: run each offer through a roof loan calculator before you trust the printed numbers. Type in the amount financed, the term, and the APR, and see whether the calculator's monthly payment lands near what the lender printed. Lenders make arithmetic mistakes too, and a simple sanity check catches the ones that cost you. A roof loan calculator is also the fastest way to translate "two points lower APR" into a real monthly figure — usually a smaller difference than the salesperson implies, and a bigger difference in total interest than they'd like to admit. Use the calculator to verify, not to daydream: the printed disclosure is the legal truth, and the calculator is your second opinion.
The Decision Rule
After the columns are filled and the math checks out, the decision actually gets simple. If the totals of payments are close, the monthly payments are affordable either way, and the terms on paper are comparable — then the roof price and your trust in the contractor decide it. That's the sign of roof financing contract terms doing their job: once the columns match, the rest of the decision gets easy. That's how it should be. Financing is a tool you compare and then set aside; it shouldn't be the reason you pick one roofing company over another.
But if the offers disagree on the total of payments by thousands of dollars, that disagreement is the entire conversation. Ask the more expensive offer why it costs more, in writing, and see if the answer holds up after a night's sleep. In my experience, the offer that can explain itself plainly is usually the one worth signing — and the offer that gets defensive is the one worth walking away from. Before you sign, make the payment make sense.