When homeowners decide to finance a new roof, the sales pitch almost always leads with a monthly payment, and that one number gets all the attention. After a decade of sitting across kitchen tables while financing offers were explained — and sometimes half-explained — I can tell you the payment is the last number I check. The three numbers that actually tell you whether a deal is sane are the APR, the term, and the total cost. If you only compare monthly payments, you can walk away convinced two offers are basically the same when one of them is quietly thousands of dollars more expensive. Learn these three numbers, and no lender or contractor will ever again hide a rough deal behind a smooth monthly figure.
The Three Numbers, Translated Into a Homeowner's Words
Lenders love their own vocabulary, so here is each number the way I explain it to a neighbor across the fence.
What the APR Really Means
The APR is the yearly cost of borrowing, written as a percentage, and it captures more than the interest rate — it folds in certain fees the lender charges, which is why it can run higher than the "rate" printed on the flyer. Think of it as the price tag on the money itself. Two loans can advertise the same interest rate and still carry different APRs if one of them adds fees on top. When you finance a new roof through a contractor's partner lender, that fee disclosure matters even more, because the dealer markup is rarely labeled.
What the Term Really Means
The term is how long you agree to make payments — 60 months, 84 months, 120 months. The term does two jobs at the same time. It sets the size of your monthly payment, and it decides how many times that payment gets multiplied. A longer term makes each payment smaller and makes the grand total bigger, and that trade-off is the most under-explained piece of loan math I know.
What Total Cost Really Means
The total cost is everything you hand over if you make every scheduled payment — every dollar of the borrowed amount plus every dollar of interest and fees. Most finance agreements state it somewhere, often buried on page three. It is the number that keeps you honest, because it turns "a payment I can afford" into "what this roof actually costs me over time." Anyone who decides to finance a new roof without looking at this number is making a budget decision with half the information.
The Same $18,000 Roof, Priced Two Different Ways
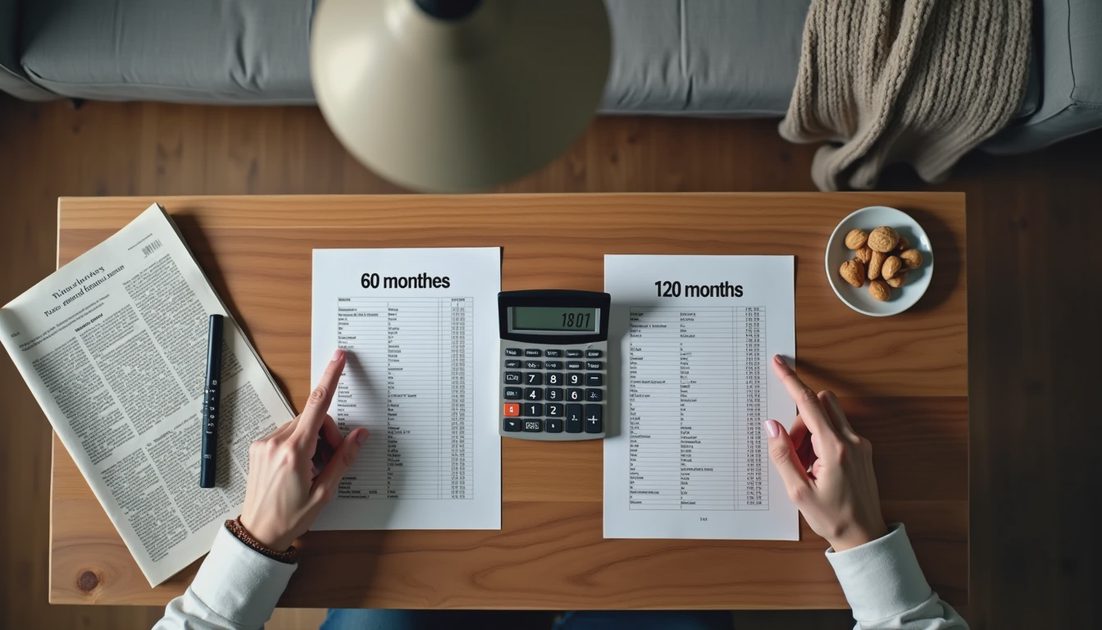
Here is why the three numbers have to be read together, using an 1,000 financed runs roughly 18,000 loan lands near 21,400 in total payments. Now stretch the same loan to 120 months at the same rate: every 12 a month, which puts the payment near 25,900, because you are paying interest for twice as many months.
Offer | APR (illustrative) | Term | Approximate monthly payment | Approximate total of payments |
|---|---|---|---|---|
Offer A | about 7% | 60 months | roughly $356 | about $21,400 |
Offer B | about 7% | 120 months | roughly $216 | about $25,900 |
Same rate, same roof, same lender. Offer A is about 356 a month" on the same 30,000. Nothing about the monthly number warned you. Only the term and the total cost reveal what is happening.
Use a Roof Loan Calculator to Reverse-Engineer Any Offer
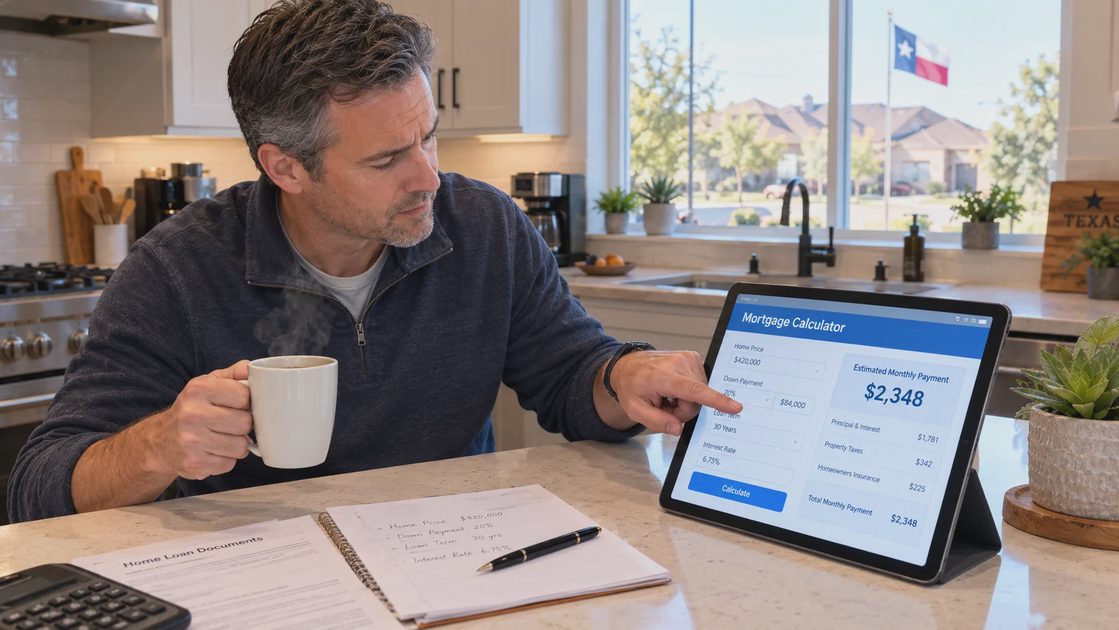
You should not have to take anyone's word for the math, and you do not. A roof loan calculator is the tool I tell every homeowner to keep open on their phone during a roofing quote. Feed it the loan amount, the term, and the APR, and it will show you what the payment ought to be before the salesperson ever quotes one. If the payment on the actual contract runs higher than the calculator says for that APR and term, something extra got added — a fee, a markup, or a rate higher than the one you were quoted out loud. If the payment looks lower, check the term; someone probably stretched the months out to make the number look friendlier. Either way, the calculator does not argue, and it does not need the sale. If you are going to finance a new roof on a contractor's timeline, run the numbers yourself first.
Here is the short list of numbers to ask for before you say yes to any financing offer:
The APR — not "the rate," the APR — in writing on the document.
The term, in months, spelled out clearly.
The total of all payments if you make every scheduled payment.
Confirmation that the payment on the contract matches the calculator math for those three numbers.
The payoff amount if you decide to pay the loan off early, and whether any prepayment penalty applies.
The Payment Gets Advertised; These Three Numbers Are What You Live With
A salesperson can make almost any roof sound affordable by stretching the term until the payment fits your monthly budget. That is not usually malice — it is how the product gets sold — but it is exactly why the monthly payment alone is a terrible way to compare offers. When I help neighbors in Plano review financing, I open my house numbers spreadsheet and write down three things for every offer: the APR, the term, and the total cost. If a lender or contractor will not put all three in writing, that answer tells me everything I need to know about the deal. The monthly payment is what gets advertised; these three numbers are what you actually live with for the life of the loan. No matter how you choose to finance a new roof — contractor plan, personal loan, or home equity line — those three numbers travel with you for years. Before you sign, make the payment make sense.